Guide
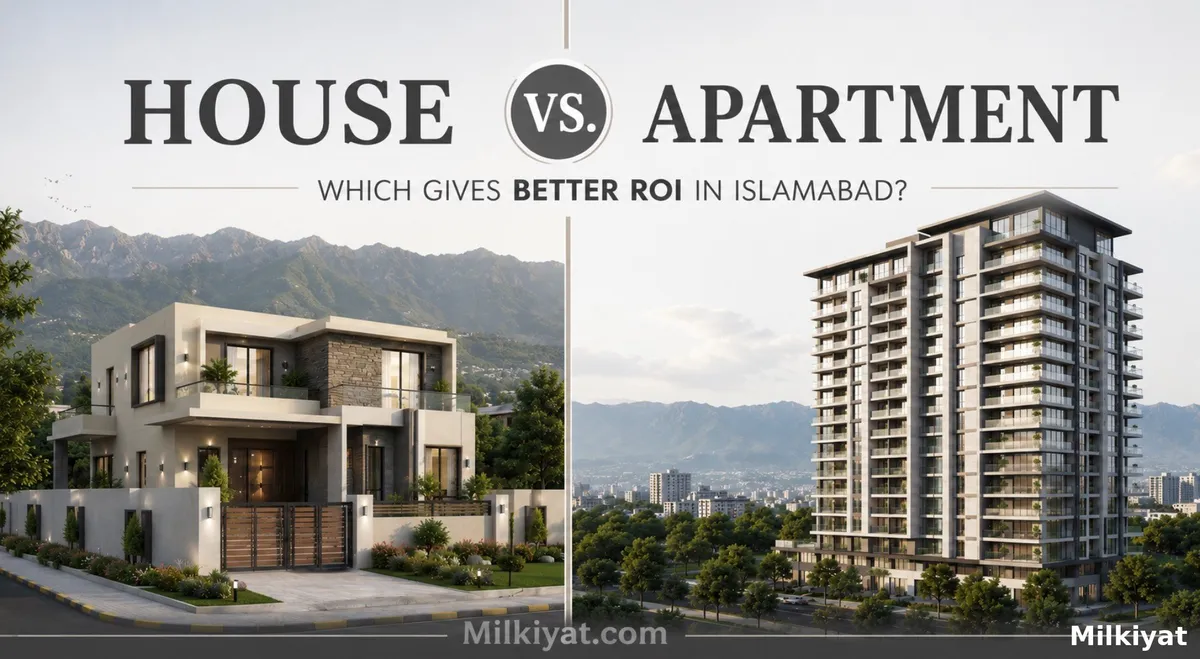
House vs Apartment Investment in Islamabad 2026: Which Is Better?
By wajahat Ali
Real Estate Analyst
Updated 8 min read
Quick answer: If your priority is long-term capital appreciation, buy a house you own the land, and land in well-located Islamabad sectors and legal societies is the durable wealth-builder. If your priority is monthly rental income, buy a high-rise apartment Islamabad's average gross rental yield is around 6.75%, among the highest of major global cities, and apartments generate cash flow faster with lower maintenance. The 2026 budget rewards holding documented assets of either type over short-term flipping.
House vs Apartment in Islamabad: The Core Difference
The single most important concept is this: land appreciates, buildings depreciate.
When you buy a house in Islamabad, you own the plot it sits on. In prime, legally clean locations, that land has historically been the engine of wealth. The structure ages and loses value, but the plot beneath it tends to climb, which is why houses remain the classic vehicle for long-term and generational wealth.
When you buy a high-rise apartment, you are buying airspace plus a share of common areas. You do not own the land outright; you own a slice of a structure that is itself a depreciating asset with a finite lifespan. In a rising market the apartment's price still increases, but its appreciation rate typically lags an independent house in the same area.
Rental Yield and Cash Flow: Where Apartments Win
Apartments generally have the edge for monthly income. Islamabad delivers an average gross rental yield of roughly 6.75% ,for comparison, London sits near 4.3%, New York around 4.9%, Paris near 4.6%, and Tokyo between 3.4% and 4.2%. A property in Islamabad can generate meaningfully more rental income relative to its value than in those cities, supported by a tenant base of expatriates, government staff, and private-sector professionals that keeps vacancy risk low.
2-bedroom units consistently deliver the best rental yield because they attract the widest tenant pool ,couples, small families, and professionals, versus 1-bed or 4-bed units.
Houses often rent for a higher absolute monthly figure but show a lower yield percentage, dragged down by higher maintenance and longer vacancy gaps. Net residential yields on long-term leasing commonly land in the 4–5% range once costs are factored in.
Gross vs net: Published yields are almost always gross, before taxes, maintenance, vacancy, and management. Net yields typically run 1.5–2% lower. Always run your numbers on a net basis.
Capital Appreciation: Where Houses Win
Here the house pulls ahead, for the land reason above. In Islamabad, the appreciation story is strongest where land is being unlocked: legally clean CDA sectors and institutionally backed societies (DHA and FGEHA joint ventures and similar) entering the development-to-possession cycle. That transition, where a plot stops behaving like pure speculation and starts behaving like a stable, livable asset, is where durable gains tend to occur.
Apartment appreciation is real in a rising market but structurally capped by the depreciating-building dynamic. An apartment can be an excellent income asset; it is rarely the best appreciation asset.
What the 2026 Budget Changed for Property Investors
The Federal Budget 2026–27 reshaped the incentives, and both asset classes are affected:
- Withholding tax relief for active filers — purchase-side WHT dropped to a baseline around 1.25% for those on the FBR Active Taxpayers List (ATL), with selling-side rates also adjusted down.
- Abolition of the 7% Federal Excise Duty (FED) on property transactions.
- Continued heavy short-term Capital Gains Tax (CGT) to discourage flipping raw files and undeveloped plots.
- First-time buyer tax credits for vertical units under roughly 2,000 sq ft, plus state-backed affordable mortgage packages , a direct incentive aimed at apartments.
The clear direction: the market now rewards documented, held, tangible assets and penalises speculation. The single biggest factor in your tax outcome is simply being on the ATL as an active filer , non-filer penalties dwarf the differences between asset types.
Liquidity: How Fast Can You Exit?
Smaller, mid-ticket assets move fastest. A 5 Marla plot or house can sell within weeks, while a 2 Kanal property may sit for months. Apartment liquidity depends overwhelmingly on the specific building: a unit in a completed, well-amenitised project by a developer with a delivery track record is liquid; a unit in a stalled or oversupplied building can be very hard to exit.
The Construction-Cost Factor (Houses Only)
If you buy a plot and build, the structure cost is now substantial. As of 2026, turnkey construction in Islamabad commonly runs PKR 7,000–8,800+ per sq ft for standard A-category homes, with premium finishing higher. Apartment buyers skip this, they buy a finished, ready-to-rent product, which is part of why apartments offer faster cash flow.
House vs Apartment in Islamabad: Side-by-Side Comparison
| Factor | House (plot + structure) | High-Rise Apartment |
|---|---|---|
| Core asset | Land (appreciating) | Airspace + common-area share (depreciating structure) |
| Capital appreciation | Stronger, long-term | Lags houses in same area |
| Rental yield (gross) | Lower (~4–5% net) | Higher; Islamabad avg ~6.75% gross, best units higher |
| Cash flow | Slower, higher absolute rent | Faster, ready-to-rent |
| Maintenance | High (owner bears all) | Lower per-unit; service charges apply |
| Upfront effort | Plot + multi-crore construction possible | Buy finished unit |
| Liquidity | Mid-size fast; large slow | Depends on building/developer |
| Best tenant unit | — | 2-bedroom |
| 2026 budget perks | Filer WHT relief, no FED | Same, plus first-time buyer credits |
So Which Should You Buy?
There is no universal winner, match the asset to your goal.
Choose a house (or plot to build) if you have significant upfront capital, a 5–7 year horizon, and your priority is long-term capital growth and wealth to pass on, and you are comfortable with lower yield and higher maintenance.
Choose a high-rise apartment if you want consistent monthly cash flow, prefer a finished asset with no construction headache, value lower per-unit maintenance, want first-time buyer tax credits or installment plans, or are an overseas investor wanting a manageable, rentable 2-bed unit in a completed, legally clean project.
For many investors the smartest answer is sequencing, not either/or: an apartment for income now, a plot or house for appreciation over the longer horizon, provided both are legally verified.
Before You Buy: Four Non-Negotiables
- Legal status. Verify the NOC and approving authority (CDA, RDA, or relevant body). A great payment plan on an unapproved project is a trap.
- Location. Proximity to main roads, commercial zones, employment hubs, and education drives both yield and resale.
- Developer track record (apartments especially). Have they actually delivered a completed building before?
- Tangibility and stage. Favour possession-ready or near-complete assets over speculative off-plan promises.
If a society's legal status is contested, treat it with caution no matter how attractive the headline numbers.
Frequently Asked Questions
Is a house or an apartment a better investment in Islamabad in 2026?
It depends on your goal. Houses are better for long-term capital appreciation because you own the land. Apartments are better for rental yield and monthly cash flow, with Islamabad's gross yields averaging around 6.75% and the best-located units higher.
What rental yield can I expect in Islamabad?
Islamabad's average gross rental yield is about 6.75%, among the highest of major global cities. Net yields run roughly 1.5–2% lower after taxes, maintenance, and vacancy. Well-located 2-bedroom apartments tend to deliver the strongest yields.
Which apartment size gives the best returns?
2-bedroom units consistently deliver the best rental yield because they attract the widest tenant pool , couples, small families, and professionals.
How did the 2026 budget affect property investors?
It lowered withholding tax for active filers, abolished the 7% Federal Excise Duty, kept heavy short-term capital gains tax to discourage flipping, and added first-time buyer tax credits for smaller vertical units. The net effect rewards documented, held assets over speculation. Being an active filer on the FBR ATL is essential to access lower rates.
What is the most important thing to check before buying?
Legal status. Verify the NOC and approving authority (CDA, RDA, etc.) before anything else, and for apartments confirm the developer has delivered completed projects before.
Disclaimer: This article is for informational purposes and reflects general market conditions as of mid-2026. Property prices, yields, and tax rules change frequently. Verify all figures, NOCs, and approvals independently before investing. Milkiyat.com is not a financial or legal advisor.