Blog
Bahria Town Phase 4 vs Phase 7 Rawalpindi: Commercial Concentration Compared

By Bibi Masooma
Real Estate AnalystVerified author
Updated 10 min read
Bahria Town Rawalpindi is as much a commercial market as a residential one, with each phase shaping where residents shop, bank, and eat. Phase 4's Civic Center and Phase 7's commercial pockets are two of its busiest trading areas, but they grew in very different ways and serve different parts of the society. If you are new to Bahria Town, Milkiyat's Bahria Town Rawalpindi area guide explains how its phases connect, which authority regulates each one, and where the main commercial hubs sit before you narrow down to a single location.
This article compares commercial activity in Phase 4 and Phase 7 for buyers, investors, and business owners weighing a shop, plaza unit, or commercial plot. Footfall and maturity matter, but so does what you pay to get in. You can browse current plots and properties for sale in Bahria Town Rawalpindi to compare live asking prices with the indicative commercial ranges covered below.
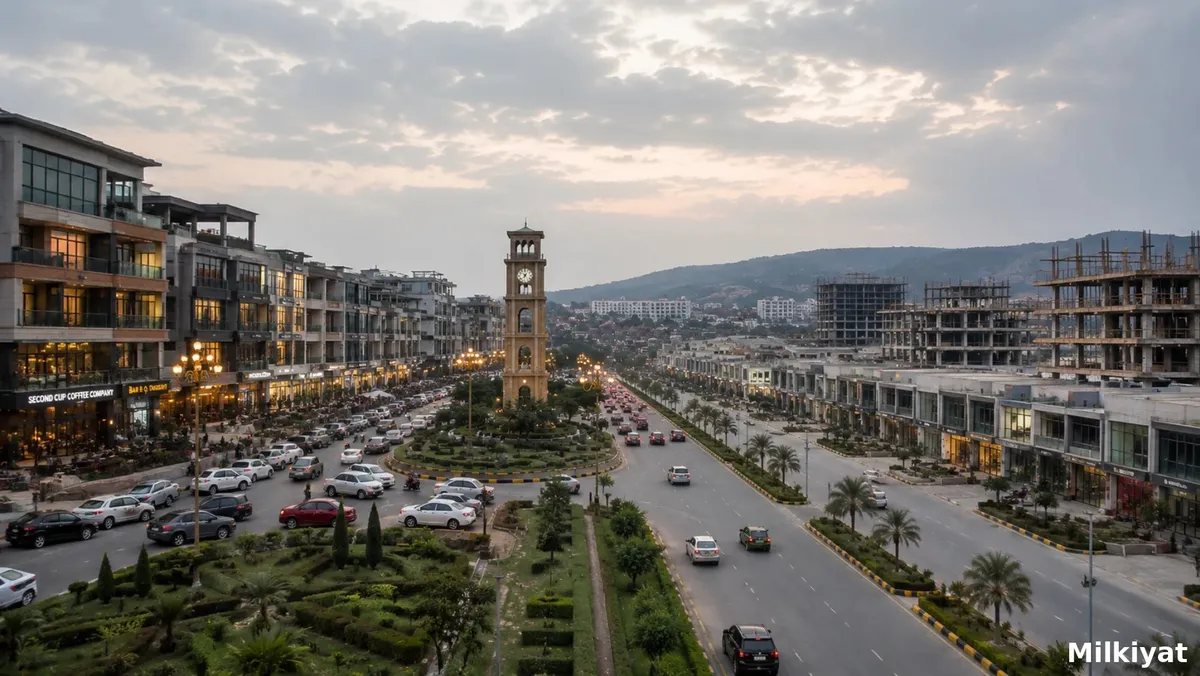
Ask a Bahria Town Rawalpindi resident where the commercial area is, and the answer depends entirely on which phase they live in. For Phases 1 through 6, it's Civic Center in Phase 4. For Phase 7 residents, it's a cluster of named commercial pockets Bahria Square, Spring North, River View Commercial that increasingly function as a feeder into Phase 8's larger Business District next door. Both are legitimate commercial concentrations. They serve different catchments, at different stages of maturity, and that difference matters more to a commercial buyer than which one has better shops.
Phase 4 vs Phase 7: Why Commercial Concentration Matters
Commercial concentration and commercial opportunity are not the same thing. A highly concentrated commercial area one with dense, established footfall tends to offer proven demand and lower vacancy risk, but often at a higher entry price and with less room for a new tenant or shop to stand out. A less mature but growing commercial pocket can offer a lower entry cost and more room to establish a new brand, at the cost of unproven footfall and a longer wait for the area to fully populate. Phase 4's Civic Center and Phase 7's commercial clusters sit on different points of that spectrum, and understanding which point you're buying into matters more than a simple "more shops equals better investment" read.
Bahria Town Phase 4 Commercial Profile
Phase 4 sits near the Soan River and hosts Civic Center, described consistently across sources as the primary commercial engine for the original Phases 1 through 6 of Bahria Town Rawalpindi. Civic Center hosts an established mix of banking, fastfood chains (including recognisable international names), and retail the kind of tenant mix that reflects years of settled demand rather than a newly opened commercial strip. Because Civic Center serves the entire Phase 1–7 catchment area, not just Phase 4's own residents, vacancy in the area has historically stayed low; it functions less like a single phase's local market and more like the commercial downtown for the whole original Bahria Town footprint.
Indicative market data for Civic Center-area commercial plots (drawn from third-party market commentary, not an official price schedule) put 5 Marla commercial plots roughly in the PKR 57.5–70 million range, with larger plots of 15 Marla and above ranging much wider depending on frontage and exact location, and small retail shop resale values commonly cited in the PKR 5.5–15 million range. These figures should be treated as indicative market observations rather than verified transaction data, and any buyer should confirm current asking and transacted prices directly through a licensed dealer or the society's own sales record before relying on them.
Bahria Town Phase 7 Commercial Profile
Phase 7's commercial footprint is more distributed than Phase 4's single dominant hub.
Named commercial pockets River View Commercial (closer to GT Road and generally cited as the more affordable entry point within Phase 7), Bahria Square Commercial (positioned on Bahria Expressway near the DHA Phase 1 bridge), and Spring North Commercial (roughly 365 plots split across 5, 8, and 10 Marla sizes) together host food chains, fashion retail, and banking similar in character to Civic Center's tenant mix, but spread across several smaller nodes rather than one central district. Phase 7's commercial area also functions as a feeder toward Phase 8's Business District, which several sources describe as the primary commercial engine not only for Phase 8 but for Phase 7 as well meaning Phase 7's own commercial identity is increasingly tied to what gets built next door rather than standing entirely on its own.
Where Is Commercial Activity More Concentrated?
On the available evidence, Phase 4's Civic Center represents the more concentrated, singular commercial hub one location, long-established, serving a wide catchment across multiple phases. Phase 7's commercial activity is real but more dispersed across several named pockets of varying maturity, several of which were explicitly marketed at different points in time as the first or cheapest commercial launch within the phase language that itself signals staggered, incremental development rather than one settled centre. For a buyer specifically prioritising proven, concentrated footfall today, Civic Center is the stronger case. For a buyer comfortable with a more distributed commercial landscape that is still knitting itself together and increasingly linked to the much larger Phase 8 Business District Phase 7's commercial pockets represent a different, earlier-stage opportunity.
Commercial Nodes at a Glance
| Commercial Node | Phase | Character | Catchment |
|---|---|---|---|
| Civic Center | Phase 4 | Single, long-established hub; banking, fast food, retail | Serves the entire original Phase 1–7 footprint |
| River View Commercial | Phase 7 | Entry-level/cheapest commercial launch within Phase 7 | Local Phase 7 residents, GT Road-adjacent traffic |
| Bahria Square Commercial | Phase 7 | Positioned on Bahria Expressway, linked to DHA Phase 1 via bridge | Phase 7 plus DHA Phase 1 spillover |
| Spring North Commercial | Phase 7 | ~365 plots (5/8/10 Marla); food, fashion, banking brands | Local Phase 7 residents |
| Business District | Phase 8 | Largest single commercial hub across Phase 7 and 8; some towers still under construction | Phase 8 primarily, plus Phase 7 |
Compiled from developer and market commentary descriptions cited in the sections above; footfall and maturity for each node should be confirmed by a site visit, not assumed from this table alone.
Indicative Commercial Pricing (Civic Center Area)
| Category | Indicative Price Range |
|---|---|
| 5 Marla commercial plot | PKR 57.5 million – 70 million |
| 15 Marla+ commercial plot | PKR 200 million – 450 million |
| Small retail shop (resale, under ~500 sq ft) | PKR 5.5 million – 15 million |
| Corporate office rental (2,500+ sq ft) | PKR 170,000 – 450,000 per month |
Drawn from third-party market commentary on the Civic Center area, not an official price schedule. Comparable published figures for Phase 7's commercial nodes were not available in the sources reviewed confirm current asking and transacted prices directly with a licensed dealer before relying on any figure here.
Retail, Services and Footfall
Civic Center's footfall benefits from decades of accumulated residential density across Phases 1 through 6 feeding into one location, plus its position as effectively the only major commercial centre for that entire original footprint there is limited competing commercial supply pulling shoppers elsewhere within those phases. Phase 7's footfall is split across its own residential base plus through traffic between Phase 7 and the Phase 8 Business District, meaning individual commercial pockets within Phase 7 depend more on their specific location relative to that traffic flow than Civic Center's more centralised position does.
Commercial Property Demand
Demand signals differ by buyer type. An investor seeking a stabilised, income-producing asset with established tenant demand and lower vacancy risk has historically gravitated toward Civic Center, reflected in the consistently low vacancy commentary around it. A buyer or small business owner looking for a lower entry cost with room to build a customer base from an earlier stage has more options within Phase 7's newer commercial pockets, accepting the trade-off of less proven footfall in exchange for that lower entry price. Milkiyat's own analysis of Bahria Town Rawalpindi's commercial performance places yields across the Civic Center (Phase 4), the Phase 7 commercial hub, and the Phase 8 Business District broadly in the 7% to 9% range, attributing this to high population density and consistent footfall across Bahria Town's commercial nodes generally, rather than isolating one phase as categorically superior to the others.
Mature Commercial Cluster vs Expanding Activity
Civic Center is, by most available evidence, the more mature commercial case: it has had the longest time to establish its tenant mix, footfall patterns and brand presence, while serving the broadest catchment of any single commercial node in the original Bahria Town Rawalpindi footprint. Phase 7's commercial pockets represent expanding activity, with growing retail and food options but a less settled commercial identity. Neither is inherently the "better" commercial buy; the choice depends on whether a buyer prioritises proven demand and established activity or lower-entry growth potential.
For regulatory and planning verification, buyers should check the relevant authority based on the exact phase and location through the official websites of Rawalpindi Development Authority (RDA) and Capital Development Authority (CDA).
What Buyers and Business Owners Should Check
-
Which specific commercial node within Phase 7 (River View, Bahria Square, Spring North, or others) a plot sits in, since footfall and maturity vary meaningfully between them “Phase 7 commercial” is not one uniform market.
-
Current occupancy and vacancy rates for the specific plaza or commercial block being considered, gathered from a site visit rather than marketing material alone.
-
The plot's NOC or layout-plan status. Bahria Town Rawalpindi's jurisdiction is genuinely split by phase Phases I, II, III and VIII generally fall under Rawalpindi Development Authority (RDA), while Phases III-E, IV, V, VI, VII and VII-E generally fall under Capital Development Authority (CDA). The correct regulator to verify against therefore depends on the exact phase and block, not simply the “Bahria Town” name.
-
Rent per square-foot and vacancy comparisons across a few comparable units in the immediate area, rather than relying on a single dealer's yield estimate for the whole phase.
-
The pace of tenant brand additions over the past 12–24 months in the specific node a useful, if informal, proxy for whether footfall is genuinely growing or has plateaued.
FAQs
Which Bahria Town phase has more established commercial activity? Phase 4's Civic Center is the more established, concentrated commercial hub, serving the broadest catchment across the original Phases 1–6. Phase 7's commercial activity is real but more distributed across several smaller, newer pockets.
Is Phase 4 better for commercial property? It depends on the buyer's priority. Phase 4 suits a buyer seeking proven footfall and lower vacancy risk. Phase 7 can suit a buyer seeking a lower entry cost with room to grow alongside the area, accepting less proven demand in return.
How does commercial concentration affect rental demand? Higher concentration generally means more consistent footfall and lower vacancy risk, but often at a higher entry price. Lower concentration can mean a cheaper entry point but less predictable, still-developing demand.
What should buyers check before purchasing commercial property? The specific commercial node's occupancy and vacancy levels, the plot's exact NOC/layout-plan status and regulator (RDA or CDA, depending on the phase), and comparable rent and footfall data gathered directly rather than from a single dealer estimate.
Internal Links Used:
- https://milkiyat.com/articles/dha-islamabad-vs-bahria-town-rawalpindi-which-offers-better-returns
- https://milkiyat.com/articles/rda-vs-cda-jurisdiction-which-is-better-for-your-investment
Official Sources Used:
Note: Commercial pricing figures cited in this article are drawn from third-party market commentary rather than an official price schedule and should be independently verified before any purchase decision.